
Required minimum distributions are one of the few parts of retirement planning that come with a firm annual deadline and a real penalty attached, and the first year of withdrawals often brings more questions than retirees expect. The rules determine how much must come out of tax deferred accounts each year, which accounts are included, and when the money has to be withdrawn, and they have changed several times in recent years.
This guide covers what triggers an RMD, how the deadlines and penalties work, why inherited IRA RMD rules add complexity for beneficiaries, and how a qualified charitable distribution can fit into the picture for retirees who give regularly. With the year end planning season approaching, it is a good time to look at where your own timeline stands.
What Are Required Minimum Distributions?
Required minimum distributions are the minimum amounts that owners of tax deferred retirement accounts must withdraw each year once they reach a certain age. They apply to traditional IRAs, SEP and SIMPLE IRAs, and most employer sponsored plans such as 401(k), 403(b), and 457(b), and withdrawals are typically taxed as ordinary income.
The amount is calculated by dividing the account’s balance as of December 31 of the prior year by a life expectancy factor from the IRS Uniform Lifetime Table. As a simple illustration, a 73 year old with a $1,000,000 IRA balance would use a factor of 26.5, which works out to a required distribution of roughly $37,700. The factor gets smaller each year, so the percentage that must come out gradually increases with age.
Roth IRAs do not require distributions during the original owner’s lifetime, and starting in 2024, the same became true for Roth accounts inside employer plans like a Roth 401(k).
When Do RMD Rules Apply?
Under current RMD rules, most people born between 1951 and 1959 begin required minimum distributions at age 73. For those born in 1960 or later, the SECURE 2.0 Act pushes the starting age to 75. If you are still employed and participating in your current employer’s plan, you can generally delay RMDs from that specific plan until you retire. This exception does not apply to IRAs or to anyone who owns 5% or more of the business.
How you satisfy your RMDs also depends on the type of account. If you own several traditional IRAs, each one’s required amount is calculated separately, but the total can be withdrawn from any one or a combination of them. Employer plans like 401(k)s are stricter, and each plan’s RMD must be taken from that plan. Some retirees choose to consolidate old workplace plans into a single IRA partly to simplify this step, though that decision comes with its own considerations.
Understanding the RMD Deadline
The RMD deadline is December 31 of each year, with one exception. For your very first required distribution, you can wait until April 1 of the year after you reach your RMD age. The tradeoff is that your second distribution is still due by December 31 of that same year. Two taxable distributions in one calendar year can push income higher than expected and may affect your tax bracket, Medicare premiums, and how much of your Social Security benefit is taxed.
After the first year, it helps not to wait until the final weeks of December, when custodians are handling a high volume of requests.
What Happens If You Miss a Required Minimum Distribution?
Missing a required minimum distribution, or withdrawing less than the full amount, can trigger an excise tax on the shortfall. According to the IRS, that excise tax is 25% of the amount that should have been withdrawn, reduced to 10% if the missed distribution is corrected in a timely manner, generally within two years. If a distribution is missed, the usual path is to take the shortfall as soon as possible and report it on IRS Form 5329, and the IRS may waive the penalty when the error was reasonable and is being corrected.
Inherited IRA RMD Rules Add Another Layer
For account owners who passed away in 2020 or later, most non spouse beneficiaries can no longer stretch withdrawals across their own lifetime. Instead, they generally must empty the inherited account by December 31 of the year that includes the 10th anniversary of the original owner’s death. This is commonly called the 10 year rule.
Inherited IRA RMD rules also depend on whether the original owner had already started taking their own RMDs. If they had, the beneficiary typically must take annual RMDs in years one through nine and still empty the account by the end of year 10. The IRS waived penalties for missed annual distributions under this rule from 2021 through 2024, and annual withdrawals became required starting in 2025.
Some beneficiaries fall into a group the IRS calls eligible designated beneficiaries, and they may still be able to take distributions over their life expectancy. This group includes:
- A surviving spouse
- A minor child of the original owner, until the child reaches the age of majority
- A beneficiary who is disabled or chronically ill
- A beneficiary who is not more than 10 years younger than the original owner
For everyone else, waiting until year 10 to withdraw everything could mean a large taxable distribution in a single year, often during a beneficiary’s peak earning years. Because these rules interact with estate plans, trusts, and individual tax situations, it is worth reviewing them with qualified tax and legal professionals.
Using a Qualified Charitable Distribution to Satisfy Required Minimum Distributions
For retirees who already give to charity, a qualified charitable distribution, often called a QCD, can be an efficient way to handle RMDs. A QCD is a direct transfer from your IRA to an eligible charity. Once you reach age 70 and a half, you can give up to $111,000 in 2026 this way, a limit adjusted for inflation each year. The amount counts toward your RMD but is excluded from your taxable income.
That exclusion matters more in 2026, since new rules limit how much of the charitable deduction some itemizers can use. Because a QCD keeps the distribution out of your income in the first place, it works whether or not you itemize. A few details matter:
- The money must go directly from the IRA custodian to the charity.
- Donor advised funds and private foundations are not eligible recipients.
- The transfer must be completed by December 31 to count for that tax year.
There is also a one time option to direct a QCD to a charitable remainder trust or charitable gift annuity, up to an inflation adjusted limit. For charitably inclined families, that is where RMD planning starts to connect with broader trust and legacy planning, and understanding how different trust structures work becomes part of the conversation.
Planning Ahead: Building Required Minimum Distributions Into Your Retirement Income Plan
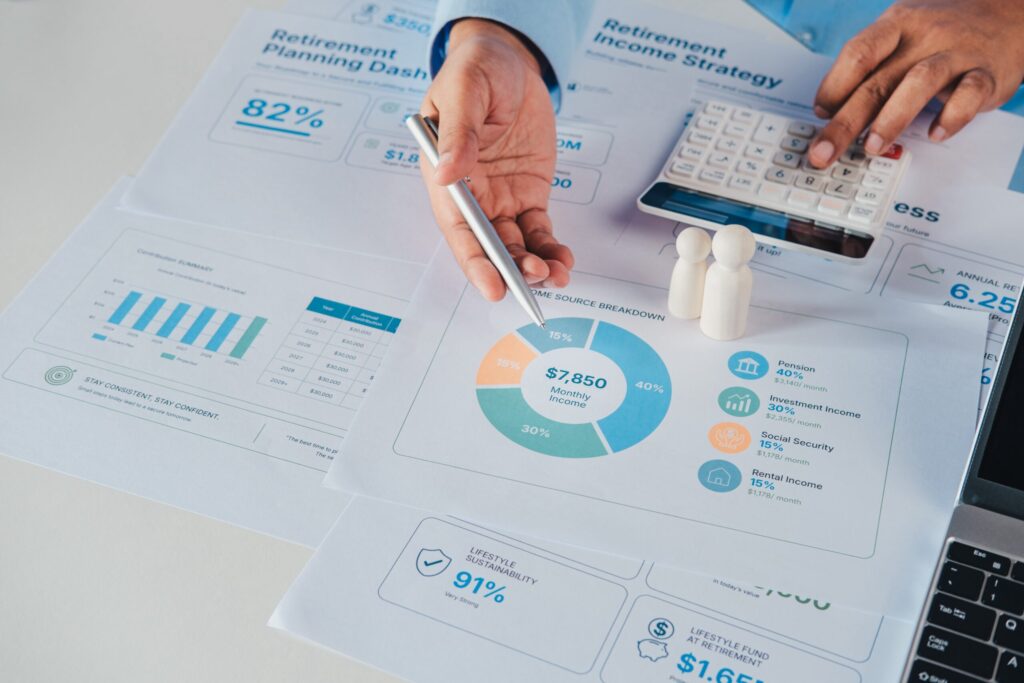 Required minimum distributions tend to create fewer surprises when they are treated as part of a coordinated strategy. The years between retirement and your RMD starting age can be especially valuable. During that window, some retirees draw from tax deferred accounts gradually or consider Roth conversions, which may help reduce future required amounts and smooth out taxable income. Whether that makes sense depends on your current bracket, expected future income, and legacy goals.
A disciplined, rules based approach applies here just as it does in portfolio management. Knowing in advance which accounts you will draw from, when, and in what amounts takes the guesswork out of the process. That kind of structure is at the heart of a well built retirement income plan.
Smart Questions to Ask About Your RMD Timeline
- What year do my RMDs begin, based on my birth year?
- Would delaying my first RMD into the following year create a larger tax bill overall?
- Have I inherited an IRA that may require annual withdrawals under the 10 year rule?
- Could a qualified charitable distribution support my giving while reducing taxable income?
Required Minimum Distributions Work Best as Part of a Plan
Required minimum distributions are not optional, but how you prepare for them is. When your taxes, income, and charitable goals are coordinated with a fiduciary minded perspective and a clear process, RMDs become a planned part of retirement rather than a year-end scramble.
Frequently Asked Questions
Can I withdraw more than my required minimum distribution?
Yes. The RMD is only the minimum, and you can withdraw more at any time. However, withdrawing extra in one year does not reduce the required amount for future years.
Do I have to take an RMD if I am still working?
You can generally delay RMDs from your current employer’s plan until you retire, unless you own 5% or more of the company. RMDs from IRAs and former employers’ plans still apply.
Do inherited Roth IRAs have required minimum distributions?
Yes. Most non spouse beneficiaries who inherit a Roth IRA are subject to the 10 year rule, although qualified withdrawals are generally tax free.
Start With a Conversation About Your RMD Timeline
Every situation is different, and the right approach to required minimum distributions depends on your account types, tax picture, income needs, and legacy goals. If you want a strategy built around your goals, it helps to start with a conversation about your RMD timeline. Reach out to Pinzker & Associates to map out when your distributions begin, which accounts they come from, and how they fit into the rest of your retirement income plan.
Securities and Investment Advisory Services offered through A.G.P. / Alliance Global Partners, Member of FINRA | SIPC.
A.G.P. / Alliance Global Partners and Pinzker & Associates are unaffiliated separate companies.